Insights
Financial Planning vs. Budgeting: What's the Difference?
By Moshe Alpert, CEO of Ceremian Financial
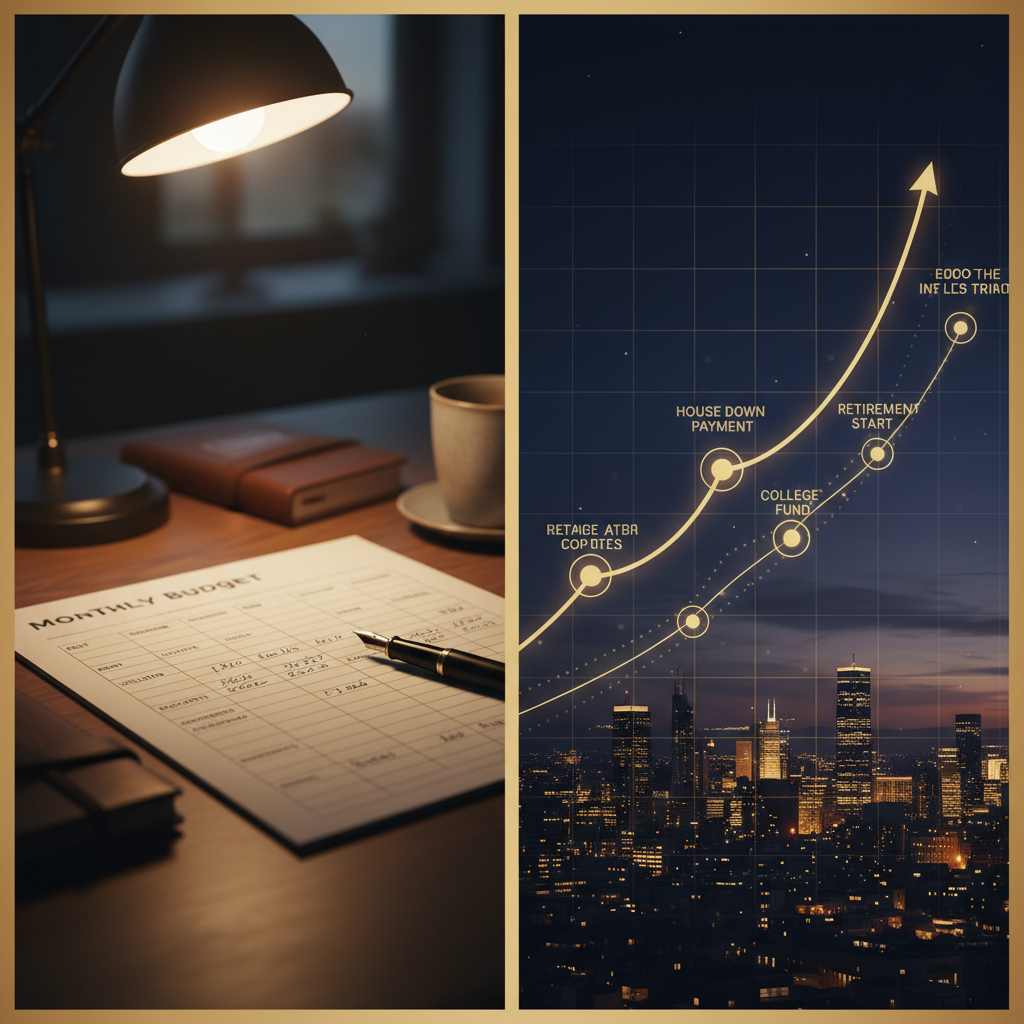
This is one of the most common questions I hear — and it's a great one. People often use "budgeting" and "financial planning" interchangeably, as if they mean the same thing. They don't.
Understanding the distinction between the two is one of the most important steps you can take toward building real, lasting wealth. Both are necessary. But they serve very different purposes — and confusing them is one of the main reasons people feel stuck financially even when they're "doing everything right."
The Short Answer
Budgeting is about managing what you have today — tracking income, controlling spending, and making sure you're not spending more than you earn.
Financial planning is about designing where you want to go over the next 5, 10, 20, or 40 years — and building a coordinated strategy across investments, taxes, insurance, retirement, and estate planning to get there.
Think of it this way: a budget is a tool. A financial plan is the blueprint.
What Is Budgeting?
A budget is a monthly (or annual) snapshot of your money. It answers questions like:
- —How much am I earning?
- —How much am I spending — and on what?
- —Am I saving anything this month?
- —Where is my money actually going?
Budgeting is fundamentally about control. It's the discipline of aligning your spending with your income so that you don't fall into debt and you have money left over to save or invest.
Budgets are short-term. They live in the present. A good budget helps you avoid financial stress day-to-day, but it doesn't by itself tell you whether you're on track for retirement, adequately insured, or building wealth efficiently.
Common Budgeting Methods
- —50/30/20 Rule — 50% needs, 30% wants, 20% savings/debt
- —Zero-Based Budgeting — every dollar gets a job
- —Envelope System — cash allocated by category
- —Pay-Yourself-First — savings come out before spending
What Is Financial Planning?
Financial planning is a comprehensive, long-term strategy that coordinates every dimension of your financial life. It answers questions like:
- —Am I on track to retire when I want?
- —How do I minimize my tax burden over time?
- —Do I have the right insurance in place?
- —What happens to my wealth if I die or become disabled?
- —How do I pay for my children's education without derailing my retirement?
- —When should I claim Social Security?
Financial planning is fundamentally about direction. It gives your money a destination — not just a limit.
A financial plan integrates your budget, your investments, your retirement accounts, your tax strategy, your insurance coverage, and your estate documents into a single, coherent picture. It's updated regularly as your life changes.
Budgeting vs. Financial Planning: Side by Side
Why You Need Both — Not Just One
Here's what I see all the time: people who are excellent budgeters but have no real financial plan. They track every dollar meticulously — and still feel like they're falling behind. Why? Because budgeting alone doesn't build wealth. It just prevents waste.
Conversely, I also see people who have an impressive financial plan on paper but can't stick to any kind of monthly budget. Their long-term projections fall apart because the short-term spending is out of control.
You need both:
- —Budgeting funds your financial plan by ensuring there's money available to invest and save each month.
- —Financial planning gives your budget meaning and motivation — because you know exactly what you're working toward.
The Most Common Mistakes People Make
1. Treating Budgeting as the Finish Line
Getting your budget under control is a great first step — but it's just that: a first step. Many people stop there and never graduate to actual wealth-building. A budget without a financial plan is like a runway without a destination.
2. Creating a Financial Plan and Ignoring Monthly Cash Flow
A financial plan assumes you're investing a certain amount each month. If your spending habits make that impossible, the plan fails. The two must be aligned.
3. Waiting Until You're "Making More Money" to Start
This is one of the costliest mistakes in personal finance. The earlier you start — even with modest amounts — the more compound growth works in your favor. Read more about how procrastination silently kills financial success.
4. Assuming a Financial Plan Is Only for the Wealthy
Financial planning is most valuable when you start early — not when you're already rich. It's the plan that helps you build wealth, not the other way around. Discover who we serve at Ceremian Financial.
Where Should You Start?
If you don't have a budget, start there. It's the foundation. Know your income, your fixed expenses, and your discretionary spending. Use the pay-yourself-first method — decide how much goes to savings before anything else.
Once you have even a basic handle on your cash flow, start working on your financial plan. This doesn't mean you need everything figured out. It means starting to ask the bigger questions:
- —What does retirement look like for me, and when?
- —Am I on track with my retirement savings?
- —Do I have life insurance and disability coverage?
- —How am I managing my tax exposure?
- —What happens to my estate if something happens to me?
These are the questions that a fiduciary financial advisor is trained to help you answer — and why working with one is often worth far more than the cost.
How Ceremian Financial Approaches This
At Ceremian Financial, we don't just hand clients a budget template and call it a day. We build comprehensive financial plans that integrate every aspect of your financial life — and then help you put the right cash flow habits in place to fund them.
We begin with what we call a Financial Discovery Audit — a deep look at where you are today across income, savings, insurance, investments, taxes, and estate planning. From there, we build a personalized strategy roadmap.
The result isn't just a budget or a plan in isolation — it's a coordinated system where every dollar you earn is working toward clearly defined goals. That's what we call Financial Serenity.
Learn more about our approach to financial planning and wealth management.
Frequently Asked Questions
Can I do financial planning without a budget?
Technically yes, but not effectively. Your financial plan will assume certain savings rates and cash flows. Without a budget, you have no way to ensure those assumptions are realistic or being met.
Is budgeting the same as financial planning?
No. Budgeting is one component of a financial plan — specifically the cash flow component. A financial plan is broader and longer-term, covering investments, retirement, insurance, taxes, and legacy planning.
Do I need a financial advisor to make a financial plan?
You can start on your own, but a fiduciary financial advisor brings expertise in areas like tax optimization, estate planning, and investment strategy that are difficult to navigate alone — and mistakes in those areas can be very costly.
How often should I review my financial plan?
At minimum once a year, and any time there's a major life change — marriage, divorce, a new child, a job change, inheritance, or approaching retirement. Your plan should evolve as your life does. See our complete guide to financial planning in 2026.
The Bottom Line
Budgeting and financial planning are not competitors — they're partners. Your budget is the engine. Your financial plan is the map. Without the engine, you go nowhere. Without the map, you go in circles.
Most people have one without the other. The goal is to have both working together — and that's exactly where the magic happens.
If you're ready to move beyond budgeting and build a true financial plan, let's talk.
Also of Interest