Insights
What Does Financial Planning Actually Include?
By Moshe Alpert, CEO of Ceremian Financial
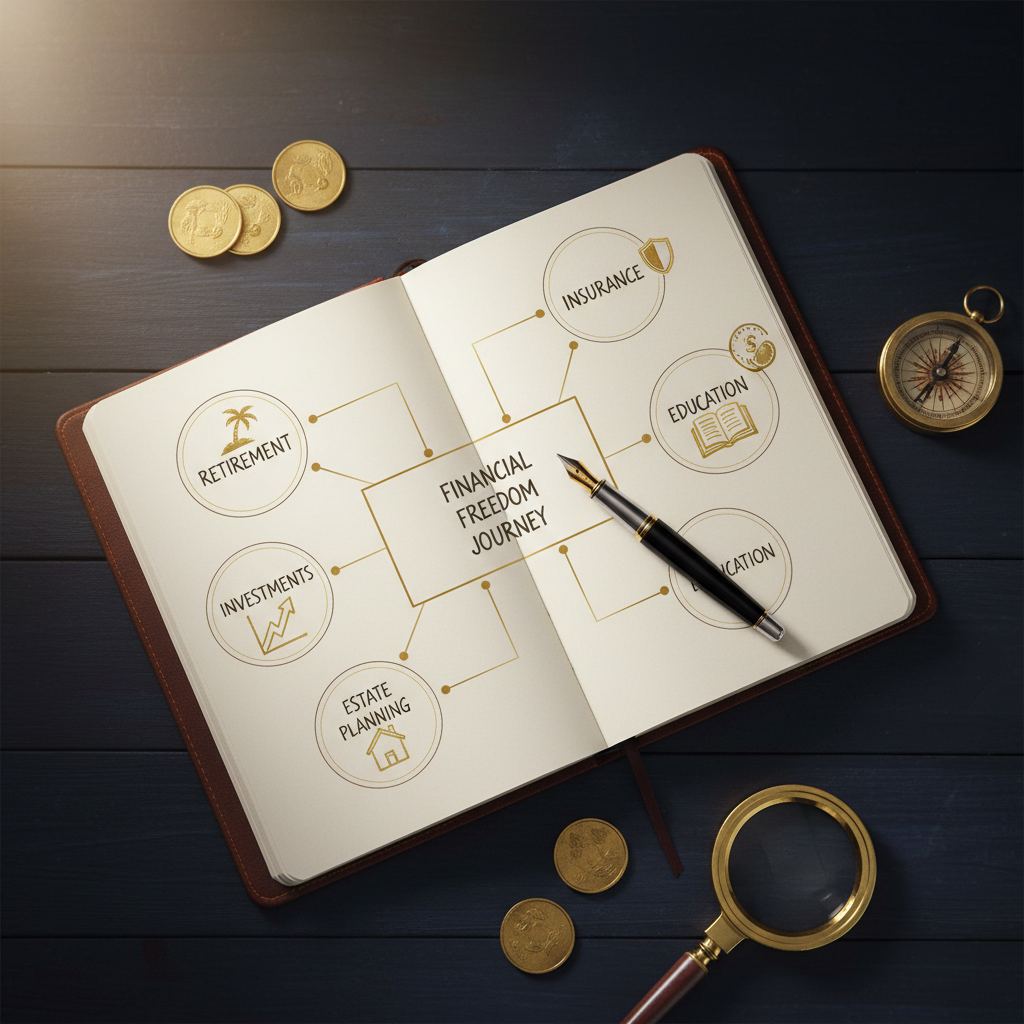
Most people hear the phrase "financial planning" and think it means picking stocks or setting up a retirement account. That's only a fraction of the picture.
A true financial plan is a comprehensive, coordinated strategy that addresses every dimension of your financial life — not just today, but across the full arc of your life. It's the difference between reacting to financial events and designing your financial future.
So what exactly does financial planning include? Let's break it down — component by component.
What Is the Financial Planning Process?
Financial planning is a structured, ongoing process — not a one-time event. A fiduciary financial advisor works with you to understand where you are, define where you want to go, and build the most efficient path to get there.
The process typically follows five key stages:
Step 1
Financial Discovery
We conduct a comprehensive audit of your current financial situation — income, assets, liabilities, insurance, taxes, and goals.
Step 2
Goal Setting
We define clear, measurable short-term and long-term financial goals that reflect your values, family situation, and vision for the future.
Step 3
Strategy Development
We build a personalized plan that integrates all relevant planning components — retirement, investments, insurance, taxes, and estate.
Step 4
Implementation
We put the plan into motion — opening accounts, repositioning assets, updating beneficiaries, and coordinating with attorneys and CPAs.
Step 5
Ongoing Monitoring
Life changes. We review and adjust your plan regularly to ensure it stays aligned with your goals as circumstances evolve.
This process is cyclical, not linear. As your life evolves — career changes, marriage, children, business transitions, retirement — your financial plan must evolve with it. Learn more about our financial planning approach at Ceremian.
The 9 Core Components of a Comprehensive Financial Plan
A well-built financial plan doesn't operate in silos. Each component connects to and influences the others. Here's what a complete plan addresses:
Retirement Planning
Helps make sure you have enough funds for a comfortable retirement through investments, savings, cash value of whole life insurance, and guaranteed income. A sound retirement plan identifies how much you need to save, when you can realistically retire, and how to structure income streams so you never outlive your money.
Explore Retirement PlanningInvestment Planning
Focuses on choosing the right mix of investments to help you reach your short and long-term wealth accumulation goals. This means building a diversified portfolio aligned with your risk tolerance, time horizon, and specific financial targets — not just chasing returns.
Explore Wealth ManagementInsurance Planning
Assesses risk and determines the right insurance solutions to help safeguard against the unexpected. Life insurance, disability coverage, and long-term care policies are the financial safety net that ensures a single event doesn't derail your entire plan.
Explore Risk ManagementEducation Planning
Finds ways to save and invest so that you can help pay for a child's educational expenses. Whether through 529 plans, Coverdell accounts, or other vehicles, the right education planning strategy ensures your children's futures don't come at the cost of your retirement.
Long-Term Care Planning
Makes sure you have a plan in place to help pay for care if you have a chronic illness or debilitating injury that keeps you from caring for yourself. Long-term care is one of the most overlooked and most expensive risks in retirement — planning ahead dramatically reduces its impact.
Estate Planning
Prepares for the distribution of assets after you pass away, including wills, trusts, and inheritance planning to protect your assets and benefit your beneficiaries. A proper estate plan ensures your legacy is preserved and transferred according to your wishes — not the government's defaults.
Explore Estate PlanningDebt Management
Develops strategies to help manage and reduce debt effectively to improve your financial stability. Understanding the true cost of debt — and building a structured payoff strategy — frees up cash flow for saving and investing, accelerating your path to financial freedom.
Tax Planning
Uses investment and insurance strategies to help minimize gains and losses as well as inheritance and estate taxes. Tax planning is not about avoiding taxes — it's about making smarter decisions year-round so you keep more of what you earn and grow.
Generational Wealth Planning
Builds a legacy that outlasts you — ensuring the wealth you've worked a lifetime to accumulate is protected, transferred efficiently, and grown across future generations. This goes beyond a basic estate plan. It includes family governance strategies, trust structures, beneficiary education, and coordinated gifting to minimize estate taxes. True generational wealth planning ensures your children and grandchildren inherit not just assets, but the values and knowledge to steward them wisely.
Explore Generational WealthWhy All 9 Components Matter Together
Here's what most people don't realize: each component doesn't just stand alone — they interact with each other constantly.
Your investment plan affects your tax plan
The way you invest — which accounts you use, how you harvest losses, when you realize gains — has a direct impact on your annual tax bill. Investment planning and tax planning must be coordinated, not siloed.
Your retirement plan affects your estate plan
IRA beneficiary designations, Roth conversion strategies, and required minimum distributions all have significant estate planning implications. A decision made in retirement planning without considering estate planning can be extremely costly for your heirs.
Your insurance plan protects everything else
Without proper risk management, a single event — a disability, a death, a lawsuit — can undo decades of careful financial planning. Insurance is the infrastructure that holds everything else in place.
Your generational wealth plan requires every other component
Building a lasting legacy isn't possible without coordinated generational wealth planning — trust structures, estate documents, gifting strategies, and beneficiary education all working together to ensure wealth is preserved and transferred with purpose.
The Most Common Mistake: Partial Planning
The biggest financial planning mistake I see is partial planning — addressing one or two components while neglecting the rest.
- —Someone who invests diligently but has no life insurance or disability coverage.
- —Someone with a solid retirement account but no estate documents — leaving their assets to be distributed by courts, not by their wishes.
- —A business owner who has built a valuable company but has no succession plan or buy-sell agreement.
- —A high earner who has never done tax planning — paying far more than necessary every single year.
Each of these is a real scenario — and each one is preventable with comprehensive planning. Read more about how procrastination silently kills financial success.
Who Needs a Comprehensive Financial Plan?
The short answer: everyone. But the components that matter most vary by life stage and situation.
Frequently Asked Questions
How long does the financial planning process take?
The initial plan can typically be developed over 2–6 weeks depending on complexity. But financial planning is an ongoing relationship — not a one-time deliverable. Plans should be reviewed at least annually and updated after major life events.
Do I need all 9 components right away?
Not necessarily. A good financial advisor will help you prioritize based on your current situation, goals, and budget. The most important thing is to have a holistic plan in place — even if some components are addressed in phases.
What's the difference between financial planning and wealth management?
Wealth management typically encompasses financial planning plus investment management for higher-net-worth individuals. Financial planning is the foundation — wealth management builds on top of it.
Is financial planning the same as budgeting?
No. Budgeting is just one component of financial health — it helps manage monthly cash flow. Financial planning is far broader, covering your entire financial life across decades, not just your monthly income and expenses.
How Ceremian Financial Builds Comprehensive Plans
At Ceremian Financial, we operate as your personal CFO — not just an investment manager. Our planning process addresses all 9 components, coordinates them into a single coherent strategy, and actively manages the plan over time.
We call the outcome Financial Serenity — the peace of mind that comes from knowing every dimension of your financial life has been thoughtfully addressed. Not just today, but for the decades ahead.
Discover who we serve and whether Ceremian Financial is right for you.
Also of Interest